Class 7 Social Science Exploring Society Part 2 Chapter 8 Solutions – Banks and the Magic of Finance
These Class 7 Social Science Exploring Society Part 2 Chapter 8 solutions cover Banks and the Magic of Finance from Exploring Society: India and Beyond (Part 2), the NCERT textbook (first edition, November 2025), used here for the 2026–27 session. The chapter belongs to the theme Economic Life Around Us and explains what financial infrastructure is, what banks do, how interest and compounding make savings grow, the role of the Reserve Bank of India, modern payment systems like UPI, the stock market, and how to stay safe from financial fraud. Below you get step-by-step answers to all Questions and activities, clear notes on key terms, extra practice, MCQs, Assertion–Reason and FAQs.
This is NCERT Part 2 Chapter 8. ClearStudy previously called it Chapter 20 by continuing Part 1; the existing address is retained.
Class 7 Social Science Exploring Society Part 2 Chapter 8 – Overview
Banks and the Magic of Finance explains financial infrastructure: banks, payment systems, stock markets and other institutions that support saving, credit and payments. Banks accept deposits and make loans subject to reserves, capital, liquidity and other rules. Interest received less interest paid is one source of income, not the same as final profit. The chapter uses simple examples to explain compound growth, RBI, financial inclusion, UPI, shares and protection against fraud.
Key Concepts & Terms
Financial infrastructure: a network of banks, payment systems, stock markets and other financial institutions that help people, businesses and the government carry out financial transactions and manage money.
Bank: a financial institution that collects money from people in the form of deposits and lends money to people or borrowers as loans.
Deposits: money held in a bank under agreed terms. Savings accounts normally earn interest and support everyday transactions; minimum balances, free transactions and fees depend on the account. Basic accounts can have no minimum balance. Current accounts support frequent business payments and generally do not earn interest; limits and charges can still apply. Fixed deposits are held for an agreed term, usually at a higher rate than ordinary savings accounts; early withdrawal depends on the product and may reduce interest or involve a penalty.
Interest: the amount charged for borrowing money or gained by lending money, usually expressed as a percentage.
Compounding: the process of earning interest on previously earned interest, so savings grow faster over time. (For example, ₹1000 at 6% grows to ₹1060 after one year and ₹1123.60 after two years.)
Loan: an amount borrowed from banks or financial institutions, with the obligation to repay it with interest at a later time.
Reserve Bank of India (RBI): India’s central bank, which began operations on 1 April 1935 and was nationalised on 1 January 1949. It was already performing central-bank functions before nationalisation. It regulates and supervises banks, acts as banker to banks and government, manages currency and carries out monetary policy. RBI issues banknotes; ₹1 notes and coins are issued by the Government of India, with RBI handling circulation.
Policy interest rate: the policy repo rate influences borrowing costs across the economy; it is decided by the Monetary Policy Committee under the monetary-policy framework. It is not the interest rate paid on every bank account or charged on every loan.
Payment system: a mechanism that facilitates the clearing and settlement of financial transactions, allowing individuals, businesses and organisations to transfer funds. Examples include cheques, debit cards, internet banking and the Unified Payments Interface (UPI).
Share & stock market: a share is a unit of ownership in a company; a collection of shares is called stock. Shares are bought and sold at a stock exchange such as the Bombay Stock Exchange (BSE, established 1875).
Other key terms: Debit (taking money out of an account), credit (receiving money in an account), PIN (a numeric code used for authentication), OTP (a one-time password), and investment (putting resources in assets expected to gain value over time).
The Big Questions — explained
1. What does financial infrastructure comprise? Banks, payment systems, securities markets and supporting financial institutions connect savers, borrowers, businesses and government.
2. What do banks do? They accept deposits, provide payment and withdrawal services, keep transaction records and lend subject to checks and rules. These services support households and businesses.
3. How does it support national progress? Reliable payments and suitable finance help production, employment and investment in physical infrastructure. Consumer protection, sound regulation and access for underserved people help make these benefits more widely available.
Source: NCERT Exploring Society: India and Beyond, Part 2 Chapter 8, pp. 193–212, first edition November 2025. Official RBI, NPCI, PMJDY and SEBI sources clarify the simplified textbook examples. Read also From Barter to Money and Infrastructure.
“Questions and activities” — Full Solutions
All questions below are reproduced verbatim from the NCERT textbook’s end-of-chapter Questions and activities section. Answers are original, written in exam-ready style.
1. What is financial infrastructure? How does it complement physical infrastructure?
2. How does having a bank account help people? Should everyone be required to have a bank account?
3. What could be the possible advantages and disadvantages of compound interest for savers and borrowers?
4. How does financial infrastructure enable the flow of money between households and businesses? Can you think of how the government can facilitate this flow?
5. What could be the reason for the higher interest rate earned on fixed deposits as compared to a savings account?
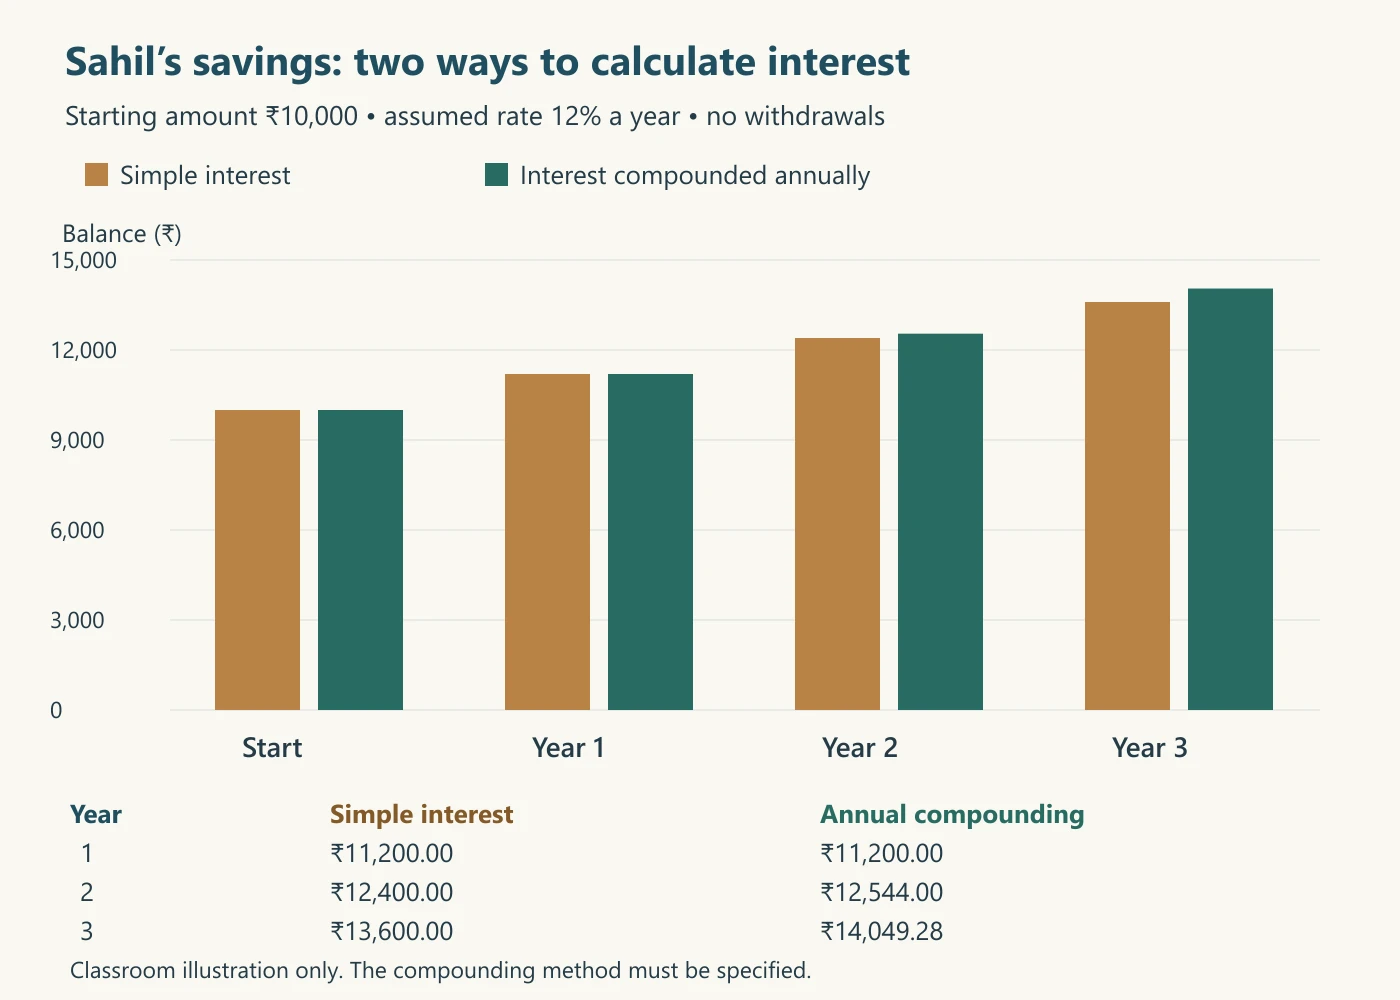
6. Sahil received ₹10,000 as a prize in a poster-making competition. His father promises to pay him 12 per cent interest per year if he does not spend the amount. After 3 years, how much money would Sahil have?
7. How does the stock market help mobilise the savings of individuals? In what ways do companies benefit by issuing shares to people?
8. How can we balance the convenience of digital payments with the risk of cyber fraud?
9. Ask your family members or neighbours about—
• how they save money?• whether they use UPI, ATM or cheques, the kinds of transactions they perform through UPI; do they find UPI better than using cash or not, and why.• if they or their acquaintance have experienced digital fraud, for instance, through a fake call or message asking for bank details. What did they do when they realised it was a scam, and what did they learn from that experience?Summarise your findings in a table or short report. Share one surprising insight with your class.
| Topic | Record from the interview |
|---|---|
| Saving methods | General methods mentioned, without amounts or account details. |
| Payments used | UPI, cash, ATM or cheque; purposes and reasons for preference. |
| Difficulties | Connectivity, accessibility, fees or other experience actually reported. |
| Scam experience | Only if they wish to discuss it: broad warning signs and action taken. |
10. Create a Financial Safety Poster.
• Design a poster with dos and don’ts of digital banking safety (for example, not sharing OTPs, reporting frauds).• Include emergency numbers or websites like https://cybercrime.gov.in or 1930 helpline.• Hang the posters in school corridors or the library.
| Do | Do not |
|---|---|
| Verify the recipient, amount and transaction status. | Share OTPs, PINs, passwords or card security codes. |
| Use official apps and keep devices updated. | Install apps or open payment links sent by unknown callers. |
| Read every payment request carefully. | Enter a UPI PIN just to receive money. |
| Report suspected fraud immediately to your bank, 1930 and cybercrime.gov.in. | Trust a caller merely because they know your name or account details. |
11. Cheques are often used to pay utility bills. Ask your parents to allow you to fill out the cheques for a few monthly payments.
12. Suppose you have to withdraw ₹10,000 from your bank account, how would you fill out the cash withdrawal slip at your bank? Let us try below!
Extra Practice Questions
These questions and MCQs are ClearStudy practice, separate from the NCERT exercise.
Short Answer Type Questions
Q1. What is a bank?
Q2. Name the three types of bank accounts and state who mainly uses each.
Q3. How do banks earn income from deposits and loans?
Q4. What was the Pradhan Mantri Jan Dhan Yojana and why was it important?
Q5. What is UPI and why has it become popular?
Long Answer Type Questions
Q1. Explain how compounding makes money grow, using an example.
Q2. Describe the role of the Reserve Bank of India in the country’s banking system.
Q3. What is the stock market? Explain shares, the stock exchange, and why share prices rise and fall.
MCQs & Assertion–Reason
1. A bank is a financial institution that:
(a) only keeps money in lockers (b) collects deposits from people and lends money as loans (c) prints currency notes (d) sells goods to customers
2. Which account is mainly meant for businesses and traders who make frequent payments?
(a) Savings account (b) Fixed deposit account (c) Current account (d) Loan account
3. Earning interest on previously earned interest is called:
(a) borrowing (b) compounding (c) discounting (d) crediting
4. Banks make money mainly because they:
(a) pay higher interest to depositors than they charge borrowers (b) charge higher interest from borrowers than they pay depositors (c) do not pay any interest (d) keep all deposits in cash
5. The central bank of India, also called the banker to banks, is the:
(a) State Bank of India (b) Bombay Stock Exchange (c) Reserve Bank of India (d) NABARD
6. The Pradhan Mantri Jan Dhan Yojana was launched in the year:
(a) 1949 (b) 2014 (c) 2016 (d) 2022
7. UPI was launched by the National Payments Corporation of India (NPCI) in:
(a) 2014 (b) 2015 (c) 2016 (d) 2020
8. A unit of ownership in a company is called a:
(a) loan (b) deposit (c) share (d) cheque
9. The Bombay Stock Exchange (BSE), one of the oldest in the world, was established in:
(a) 1875 (b) 1935 (c) 1949 (d) 2016
10. In case of digital payment fraud, one should report it on the helpline number:
(a) 100 (b) 108 (c) 1930 (d) 1800
For each Assertion–Reason question, choose: (A) Both true and the Reason correctly explains the Assertion; (B) Both true but the Reason is not the correct explanation; (C) Assertion true, Reason false; (D) Assertion false, Reason true.
A-R 1. Assertion: Banks pay interest to people who deposit money in savings accounts.
Reason: Banks lend the deposited money to borrowers and earn interest, so they share some of it with depositors and encourage saving.
A-R 2. Assertion: A fixed deposit usually earns a higher rate of interest than a savings account.
Reason: Money in a fixed deposit stays with the bank for a fixed, longer period, giving the bank greater certainty to lend it.
A-R 3. Assertion: The Reserve Bank of India can issue currency notes.
Reason: Section 22 of the RBI Act gives RBI the right to issue banknotes; ₹1 notes and coins are government issues.
A-R 4. Assertion: One should freely share OTPs and PINs with callers who claim to be from the bank.
Reason: Sharing OTPs and PINs allows fraudsters to access accounts and steal money.
A-R 5. Assertion: UPI has made digital money transfers quick and convenient in India.
Reason: UPI allows instant transfers using a QR code or phone number without filling out a cheque each time.
Exam Tips & Common Mistakes
How to write a clear answer
Learn the clear definitions of financial infrastructure, bank, deposit, loan, interest and compounding. For the numerical question, show every year’s calculation step by step (Year 1, Year 2, Year 3) and remember that interest is charged on the new total each year. Know the three account types and who uses each, the RBI’s functions (banker to banks, issues banknotes, implements monetary policy), key years (RBI 1935/1949, BSE 1875, Jan Dhan 2014, UPI 2016), and the safety rules against fraud (never share OTP/PIN; report on 1930). Use the textbook’s own examples — Navdeep and Rima, Anand and Shreya, the king-and-sage rice story, Kumar and Piyush’s UPI payment — to show you have studied the chapter.
Common mistakes to avoid
- Calculating compound interest on the original amount each year — it must be calculated on the new total (interest on interest).
- Confusing a savings account (earns interest; terms vary) with a current account (no interest, for businesses).
- Mixing up debit (money taken out) with credit (money received).
- Thinking the RBI is an ordinary bank for the public — it is the central bank, the banker to banks.
- Confusing a share (part-ownership in a company) with a loan (borrowed money to be repaid with interest).
- Leaving the activity/interview questions (Q9–Q12) blank — write your own real findings and steps.
Frequently Asked Questions
What is Part 2 Chapter 8 of Class 7 Social Science Exploring Society about?
Part 2 Chapter 8, Banks and the Magic of Finance, explains financial infrastructure, what banks do, how interest and compounding make savings grow, the role of the Reserve Bank of India, modern payment systems like UPI, the stock market and shares, and how to stay safe from financial fraud.
How much will Sahil have after 3 years on ₹10,000 at 12% interest?
Assuming yearly compounding (simple interest would give Rs 13,600): after Year 1 it is ₹11,200, after Year 2 it is ₹12,544, and after Year 3 it is ₹14,049.28 (about ₹14,049). The interest is calculated on the new total each year, so it grows faster over time.
What is the exercise heading for Part 2 Chapter 8 of Exploring Society Part 2?
The end-of-chapter exercise in Exploring Society: India and Beyond (Part 2) Chapter 8 is headed Questions and activities and contains 12 numbered questions and activities, all answered on this page.